Ramp, Brex and Pliant: Same Product, Different Positions
Three platforms sell remarkably similar capabilities. What separates them is how they control, influence or enable the three roles behind commercial card payments.
Subscriber · Sign in to listen to the audio briefing
Audio briefings are available to subscribers. Sign in with the email you used to subscribe — we'll send a one-time code.
Three deals, one product
In the space of seven months, three transactions put a price on a similar idea. Capital One closed its acquisition of Brex on April 7, in a deal announced at $5.15 billion. On October 15, Ramp raised $1.85 billion at a $60 billion valuation, reporting more than $2 billion in annualized revenue, over 85,000 customers and positive cash flow. On November 4, Berlin-based Pliant announced an $80 million Series C led by Seaya Nova and Speedinvest, having crossed $100 million in annual recurring revenue.
The product underneath all three is familiar: corporate cards, spending controls, expense automation and accounting integration. Banks and technology providers have offered variations of these capabilities for decades. What investors are valuing goes beyond the feature set. It is the position each company occupies in the commercial payments value chain.
Three roles, not three companies
A commercial card program involves three distinct roles. Someone finances the transaction, providing underwriting, credit capacity and funding. Someone manages the workflow where spending originates: requests, approvals, invoices and reconciliation. And someone supplies the infrastructure that issues cards, processes authorizations and supports clearing and settlement.
Traditionally, banks controlled financing and the customer relationship, contracted for much of the processing infrastructure, and relied on their own or third-party software to manage the workflow. My reading is that Ramp, Brex and Pliant represent three different approaches to controlling or enabling these roles.
Ramp's advantage begins with the workflow. It manages the finance team's daily activities while coordinating card issuance and credit through financial institution partners. Its revenue combines interchange, subscriptions, interest and other sources. The software strengthens the relationship; payment activity monetizes it. The more purchasing activity Ramp influences, the larger its economic opportunity.
Brex has a different opportunity under Capital One. Its software and commercial card capabilities now sit within an organization with substantial funding, underwriting and banking infrastructure. Capital One also owns the Discover network, following its 2025 acquisition. Whether meaningful Brex volume ever moves onto Discover will depend on acceptance and network economics, but no other spend platform has the option of combining workflow, banking economics and a proprietary network within one group.
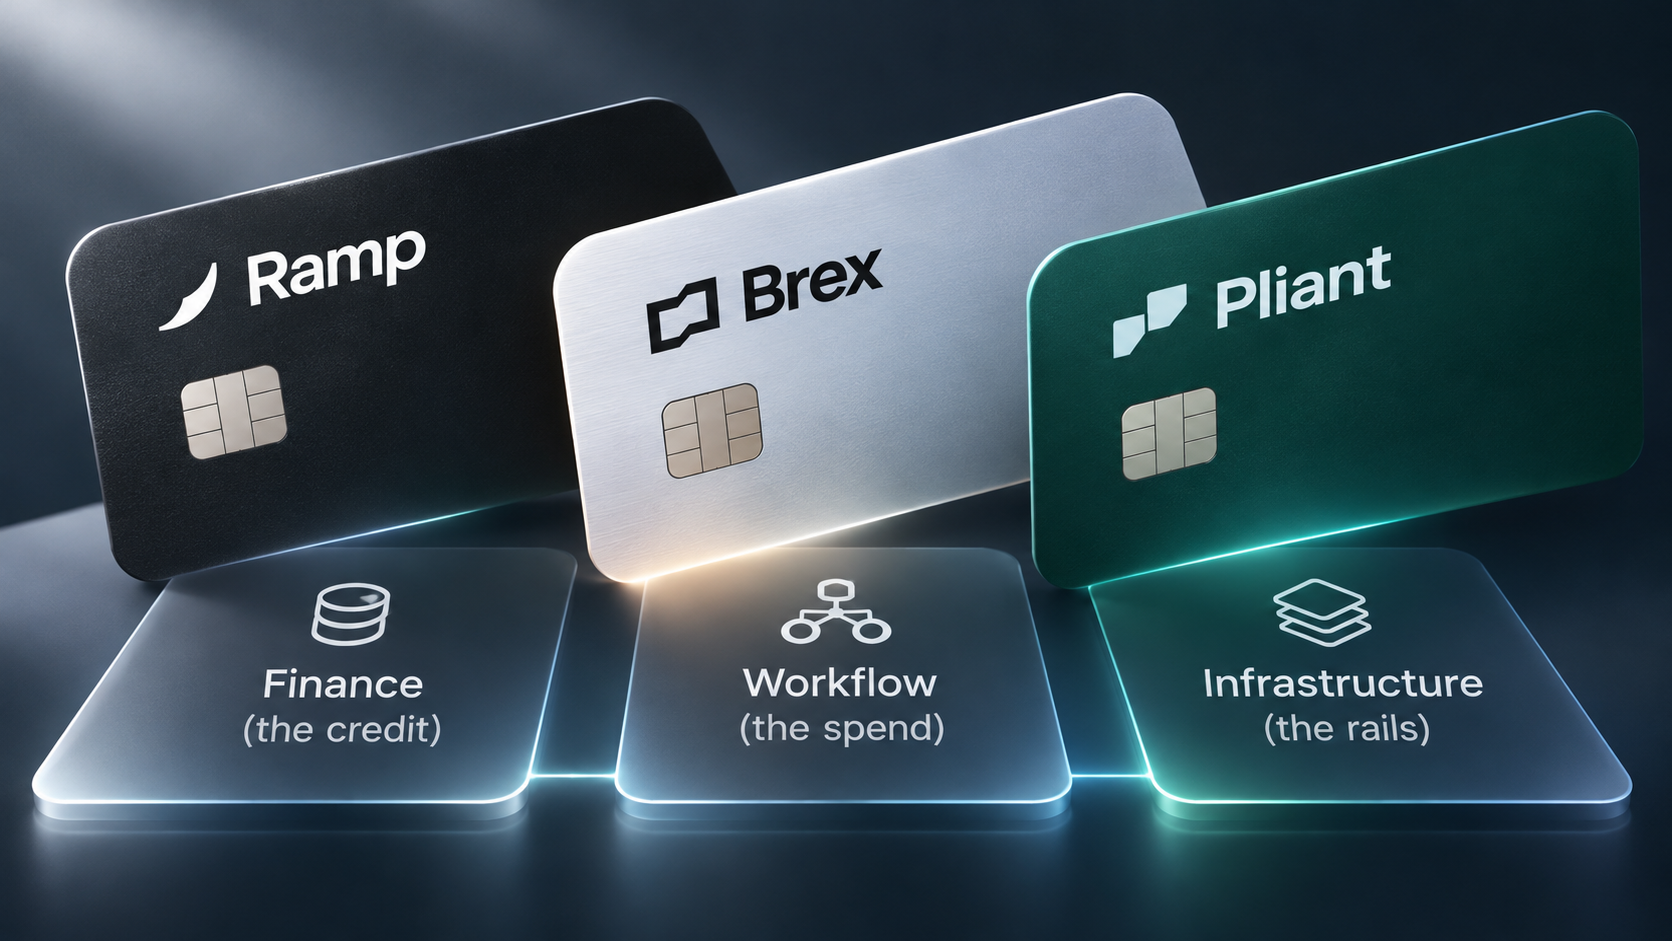
Pliant is pursuing a more distributed model. It operates commercial card programs directly, but also supplies modular card and payment capabilities to banks, fintechs and software platforms. Its latest financing supports expansion in North America and infrastructure accessible to AI agents through the Model Context Protocol. It captures a different share of the economics, but reaches customers through every partner it enables, and those partners keep the customer relationship.
The number nobody discloses
All three strategies rest, to varying degrees, on the same proposition: greater influence over the financial workflow creates opportunities to capture more payment activity. That proposition has a measurable test.
Ramp reports more than $275 billion in annualized purchase volume, but does not disclose how that volume splits between card transactions and other monetized payments. Its reported volume excludes bank transfers and non-monetized payments, so the figure should not be confused with total accounts payable activity. For a commercial card business, the question is not how much spending a platform manages, but how much of it the platform monetizes, through which products, and at what margin.
What banks should take from it
The lesson for banks is not to build another Ramp. It is to decide which parts of the commercial payments relationship they intend to control and which they are prepared to enable through partnerships. A software platform that owns the customer interface still depends on regulated institutions and processing infrastructure to execute transactions. But a bank that provides credit while remaining outside the workflow is lending to someone else's customer.
In commercial payments, controlling the card is no longer sufficient. The advantage belongs to whoever controls the decisions that determine when, where and how that card gets used.
The Payments Corner
30+ years across payments, fintech, banking, and financial infrastructure. Operator-level perspectives on the systems that move money.
The author is employed at Euronet Worldwide, a card issuer processing company. The author may own securities or assets referenced across The Payments Corner ecosystem. Content is provided for informational and editorial purposes only and should not be considered investment advice.
Related Insights
Citi's card-linked offer acquisition bets on cost, not on proven category economics
Citi's acquisition of Kard Financial rests on operational and financial logic—lower rewards spend, faster platform build—but the card-linked offer category itself has never demonstrated standalone profitability. Cardlytics, the only pure-play, has burned $1.15bn cumulatively since its 2018 IPO and generated negative shareholder equity last year.
Grab's Atome deal consolidates checkout control, not BNPL market entry
Grab is not entering buy-now-pay-later; it already operates PayLater in Southeast Asia. The US$1.49 billion acquisition of Atome integrates a consumer lending book with wallet, acceptance and settlement—collapsing the stack that card schemes and acquirers currently mediate—and hinges on regulatory approval from Singapore's competition and banking authorities.
Kraken's card is a bet on controlling the funding decision, not the transaction
Kraken's debit card—with its 2% rewards across multiple asset balances—is not a payments product disguised as one. It is a wallet-stickiness play that inverts traditional card architecture: instead of a card accessing a single account, the platform now decides which of many balances funds each purchase, moving the locus of control from the network to the issuer's financial operating system.