


The Payments Corner · Ecosystem access
Three layers of access
Operator-level analysis on payments infrastructure, embedded finance, credit systems, and the AI-assisted synthesis layer shaping the ecosystem. Enter at the layer that fits how you read.
I· Open Access
Open Access
The public reading experience. No signup required.
- Insights & analysis
- Latest Ecosystem Pulse briefing
- Research previews
Open to all readers.
II· Premium
Premium
The full intelligence stack — for people who work in the space.
- Full Markets intelligence suite
- Full Signals stream
- Friday Ecosystem Digest
- Per-category intelligence feeds
$7.00/mo or $70/yr (2 months free).
Open now · free through July 31.
III· Subscriber
Subscriber
Inside the ecosystem. Free newsletter participation.
- Full research reads + audio briefs
- Weekly editorial briefing
- Audio briefings archive
No paid subscription required.
Research · Latest
 Research Article
The stablecoin remittance case rests on the on-ramp and off-ramp, not the blockchain
A dollar-backed stablecoin offers no inherent financial return and occupies the same monetary value as fiat currency. The economic argument for stablecoins in cross-border payments depends entirely on whether they reduce the total cost of money movement—on-ramps, settlement, and off-ramps combined—and whether those savings actually reach the consumer sending the money.
All Research
European payment networks are mandating offline card capabilities across the continent, but the real challenge lies not in the terminal's ability to…
Offline authorization is not resilience — it's the foundation of it
European payment networks are mandating offline card capabilities across the continent, but the real challenge lies not in the terminal's ability to approve locally, but in how issuing infrastructure, issuer processors, and merchants manage the gap between the moment of authorization and the eventual settlement of accounts.
A framework law approved in Mexico's lower house in early October delegates the cost of digital acceptance to whoever moves last in…
Mexico Decides Who Pays to Leave Cash Behind
A framework law approved in Mexico's lower house in early October delegates the cost of digital acceptance to whoever moves last in the chain—card issuers, acquirers, or the state itself—without requiring any party to absorb it. A six-month trial that zeroed interchange at gas stations shows why: the subsidy leaked away, the regulatory ceiling on interchange removes the tool the trial used, and the law gestures toward SPEI-based QR codes as the permanent answer, leaving the market structure choice to regulators who have not yet chosen.
On September 3rd the Central Bank did not issue a payments rule.
The Regulator Writes the Screen
On September 3rd the Central Bank did not issue a payments rule. It issued an interface specification — and behind it sits exclusion from the arrangement for sixty months.
Insights · Latest
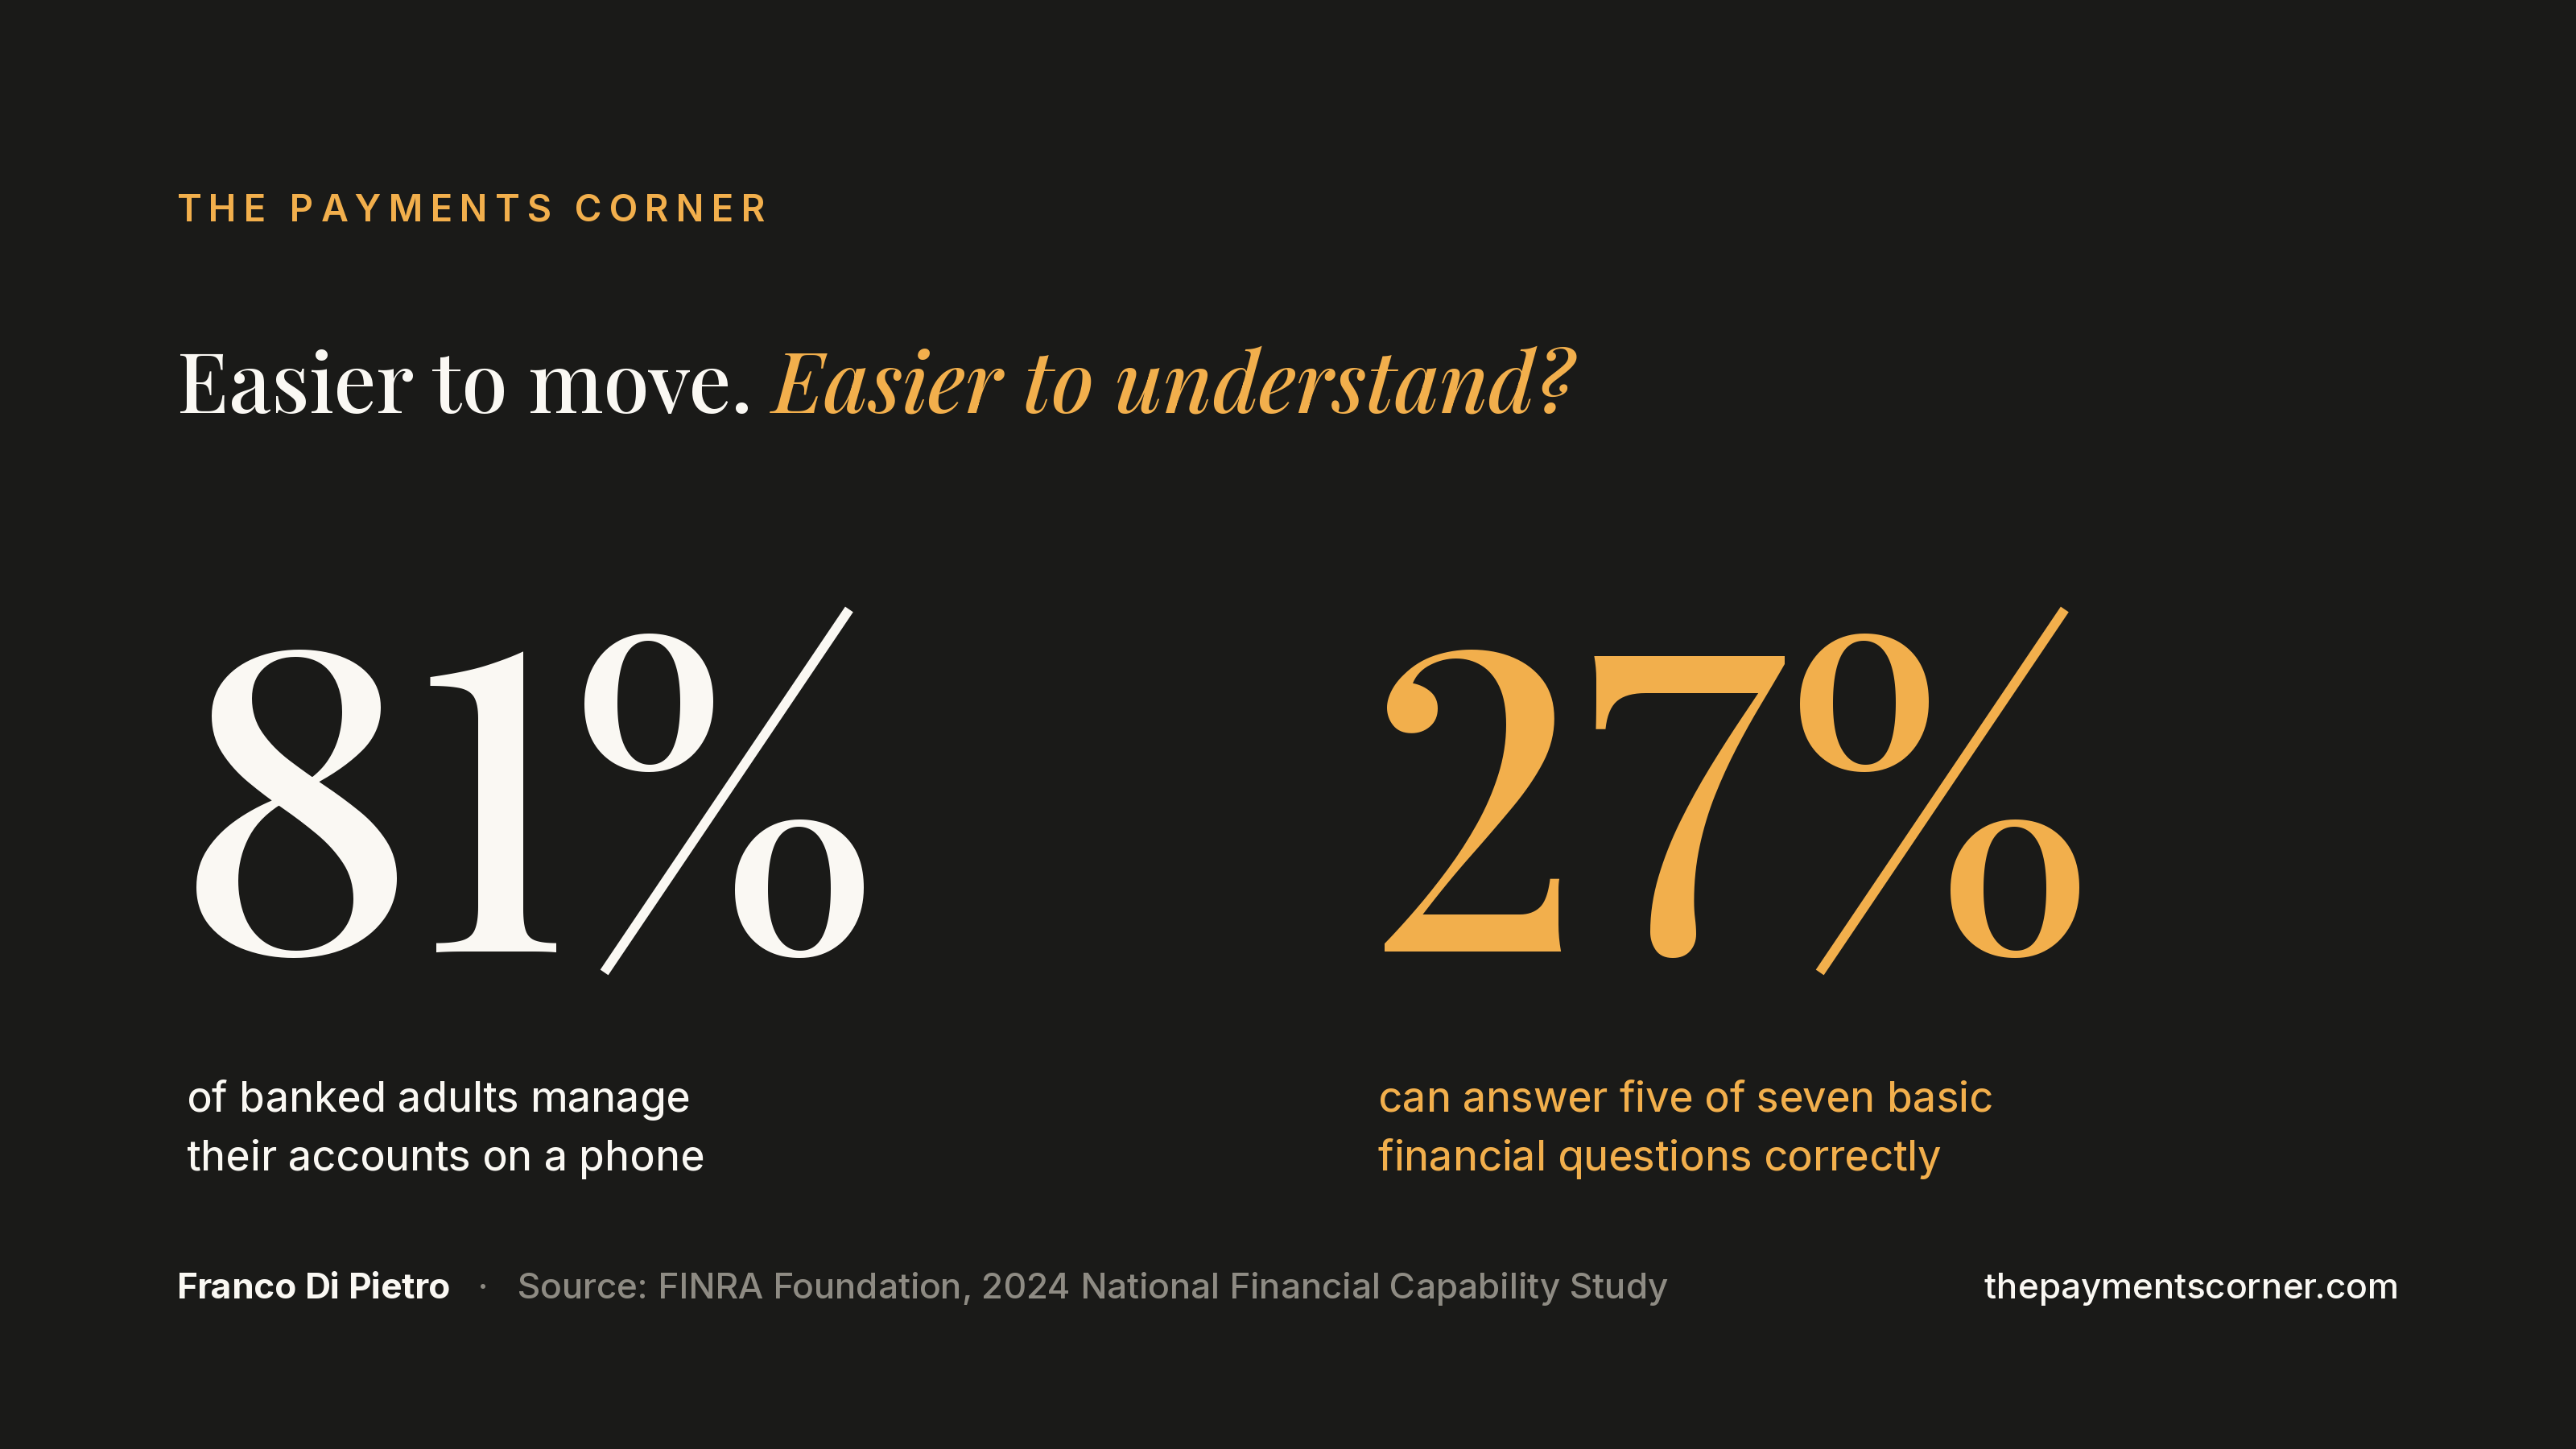
Financial institutions simplified transactions but left consumers struggling to understand the consequences
Payment infrastructure has become nearly invisible to users, but the complexity of financial obligations—credit card statements, dispute procedures, BNPL layering—remains opaque. The industry invested decades in frictionless access; it has invested far less in ensuring people understand what they are actually committing to.
All Insights
Rising cost-of-living pressure is shifting how households use payment rewards—from occasional indulgences toward deliberate, everyday value recovery.
Consumers are treating loyalty rewards as routine financial tools, not aspirational bonuses
Rising cost-of-living pressure is shifting how households use payment rewards—from occasional indulgences toward deliberate, everyday value recovery. If rewards are becoming part of baseline spending optimization rather than spending stimulation, loyalty program design and success metrics may need to reset.
Brazilian fintechs rose far more than the market after the first round and continued climbing even as the index stalled.
The Rise of Brazilian Fintechs Was a Bet on Interest Rates
Brazilian fintechs rose far more than the market after the first round and continued climbing even as the index stalled. The election was the trigger; what sustained the move was the yield curve.
Major U.S.
Banks Post Record Earnings While Stock Prices Stall on Multiple Compression Fears
Major U.S. banks delivered exceptional Q3 results—Goldman up 23% in net revenue, JPMorgan up 6%, Morgan Stanley posting record wealth management—yet their share prices fell as investors reset valuation multiples downward. The disconnect suggests markets are pricing in earnings sustainability risks rather than disputing the current numbers.
Where the payments stack stands today.
Five layers of the public payments universe, summarised at today's close. Click through for the full ticker table.
Signals From the Ecosystem
Curated developments across payments, banking technology, policy, and financial infrastructure — interpreted through an operator lens. View all →
PYMNTS
November 2026
Mastercard is extending its network rails into stablecoin liquidity pools, forcing every issuer processor that handles crypto-linked card programs to accelerate their USDC settlement and FX conversion infrastructure or cede that program volume to processors already positioned for digital asset flows. The real structural question is where interchange economics land when stablecoin backing replaces traditional credit or debit funding — and whether existing BIN sponsorship frameworks can absorb that liability model at scale.
PYMNTS
October 2026
PYMNTS
October 2026
PYMNTS
November 2026
Finextra — Payments channel
October 2026
PaymentsJournal
November 2026
PYMNTS
November 2026
Finextra — all headlines
October 2026
PaymentsDive
October 2026
Digital Transactions
November 2026
Formal, deeply-sourced research deliverables — downloadable PDFs on payments infrastructure, credit evolution, and financial technology.
BNPL and Modern Credit Architecture
 The Payments Corner
BNPL and Modern Credit Architecture
Buy Now, Pay Later is often treated as a checkout conversion tool. That framing is too narrow. BNPL is better understood as the visible edge of a deeper architectural shift: credit moving from static, account-level products toward contextual, transaction-level, embedded orchestration.
The Cooperative Advantage
Whitepaper · Cooperative Finance
The Cooperative Advantage
Why Credit Unions Are Winning the Battle for the Modern Consumer
Franco Di Pietro · The Payments Corner Research
The U.S. consumer financial services market is entering a structural reset. Federally insured credit unions now represent a systemically meaningful segment of U.S. finance, with approximately $2.43 trillion in assets, $1.72 trillion in loans outstanding, and 144.7 million members at year-end 2025. The sector generated $18.8 billion in net income in 2025, up 31.5 percent from the prior year, even as the number of federally insured credit unions continued to decline. This combination — larger aggregate scale, stronger earnings, and fewer institutions — signals that the cooperative system is not simply growing; it is consolidating into more capable, more technology-enabled platforms. This paper argues that credit unions are no longer competing only on price or affinity. Their advantage is increasingly architectural: a member-owned economic model that can recycle surplus into lower loan rates, higher deposit yields, fewer fees, and stronger member outcomes; a trusted relationship model; and a technology ecosystem that is narrowing the historical digital gap versus large banks. The future competitive question is whether credit unions can convert cooperative economics into primary financial relationships at scale through digital onboarding, real-time payments, modern credit products, data-driven lifecycle engagement, and disciplined consolidation.
Why Credit Unions Are Winning the Battle for the Modern Consumer
The U.S. consumer financial services market is entering a structural reset. Credit unions are no longer competing only on price or affinity — their advantage is increasingly architectural: a member-owned economic model translating cooperative economics into modern infrastructure.
The Future of Community Finance
Whitepaper · Community Finance
The Future of Community Finance
Technology, Scale, and the Reinvention of Regional Trust
Franco Di Pietro · The Payments Corner Research
Community banks and credit unions remain a structurally important layer of the U.S. financial system, but the economics, technology stack, and customer expectations that defined the franchise for the last half-century are being re-priced in real time. The headline aggregates are reassuring: FDIC-insured institutions earned $295.6 billion in 2025; community banks contributed $29.9 billion (up 22.5 percent year over year) and accounted for roughly 90 percent of the 4,336 insured institutions still operating at year-end; federally insured credit unions held $2.43 trillion in assets and served 144.7 million members. Beneath those totals, however, the operating model is under structural pressure. This paper argues that community finance is not disappearing — it is being structurally redefined. The next era will belong to institutions that combine local trust with platform-grade infrastructure: real-time payments rails, flexible credit and servicing systems, permissioned data infrastructure that enables 'data as collateral' in small-business lending, AI-enabled fraud and decisioning capabilities, and partnership-enabled functional scale. Drawing on FDIC, NCUA, CSBS, Federal Reserve, NBER, and recent open-banking research, we frame the future of community finance as a shift from branch-centered proximity to lifecycle-centered financial infrastructure. The strategic question is no longer whether community institutions must modernize, but where they must modernize first, which capabilities they should own, and where partnerships can create functional scale without erasing local identity.
Technology, Scale, and the Reinvention of Regional Trust
Community banks and credit unions remain structurally important, but the economics, technology stack, and customer expectations that defined the franchise for the last half-century are being re-priced in real time. The next era will belong to institutions that combine local trust with platform-grade infrastructure.
Quick insights, explained clearly
Bite-sized videos breaking down complex payments topics in minutes — across LinkedIn, Instagram, YouTube, and TikTok.
06 live

01 live
Coming soon
Instagram brief in production.
Coming soon
Instagram brief in production.
Coming soon
Instagram brief in production.
Coming soon
Instagram brief in production.
Coming soon
Instagram brief in production.
YouTube
Coming soon
Coming soon
YouTube brief in production.
Coming soon
YouTube brief in production.
Coming soon
YouTube brief in production.
Coming soon
YouTube brief in production.
Coming soon
YouTube brief in production.
Coming soon
YouTube brief in production.
TikTok
Coming soon
Coming soon
TikTok brief in production.
Coming soon
TikTok brief in production.
Coming soon
TikTok brief in production.
Coming soon
TikTok brief in production.
Coming soon
TikTok brief in production.
Coming soon
TikTok brief in production.
Follow for more insights
An editorial platform on the modern payments stack
The Payments Corner covers payments infrastructure, credit systems, embedded finance, issuer processing, and the intelligence layer reshaping the modern stack.
Coverage sits beneath the headlines: rails, settlement finality, decisioning systems, and the modernization pressure on incumbent processors, core vendors, and the institutions building around them.
The platform operates across formats — short-form video, long-form research, audio briefings, a weekly editorial cadence, and a curated stream of ecosystem signals. Each surface is authored from inside payments rather than alongside it, grounded in how the systems behave at scale rather than how vendors describe them.